
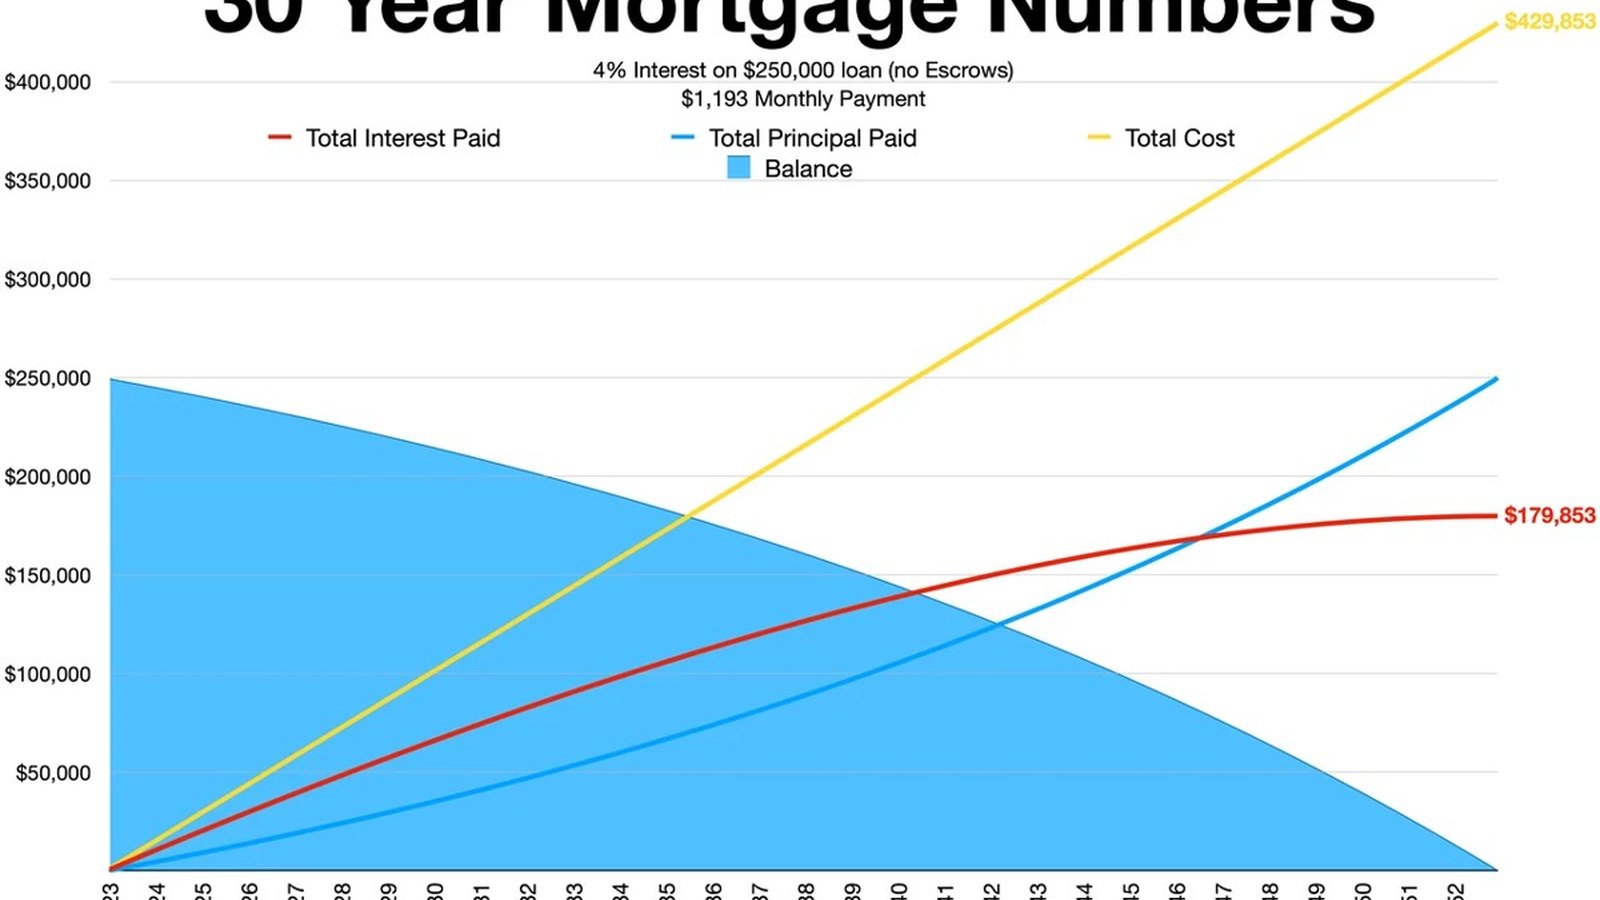
The 30-year mortgage rate averaged 7.18% this week, and first-time homebuyers are leaning harder on family money to cope. On a $300,000 loan, the principal-and-interest payment is about $1,265 a month at 3%. At 7.18%, it jumps to roughly $2,032. That is about $767 more every month for the same house, and it’s the core of a new Fortune report on first-time buyers.
Why first-time homebuyers feel the rate shock
Current homeowners are sitting on cheap pandemic-era loans. Many won’t sell, because they would trade a low rate for a high one. First-time buyers have nothing to trade. They walk straight into today’s market with no cushion (and no farewell party for a rate they never owned).
Odeta Kushi, deputy chief economist at First American Financial Corporation, put it plainly in Fortune: first-time buyers have “no low-rate mortgage to surrender.” She also told the outlet that “for many younger buyers, mortgage rates below 3% became their reference point, even though those rates were historically exceptional.”
That reference point matters. A buyer who remembers 3% sees 7% as a punishment. In reality, 3% was the outlier. You can’t miss a cheap loan you never had.
The mortgage rate numbers new homebuyers face
The latest Freddie Mac weekly survey has the 30-year fixed rate averaging 7.18% as of Nov. 5. That is down from 7.24% the week before, and it is the third straight weekly decline. A year ago, the same loan averaged 6.22%. For more on where rates have been lately, see our look at mortgage rates hitting their highest level since November 2023.
The 15-year fixed rate averaged 6.57%, down from 6.60% last week and well above the 5.50% a year earlier.
Freddie Mac chief economist Sam Khater said rates “continued their downward trajectory this week, improving the environment for prospective homebuyers against a backdrop of strong economic growth.”
Still, “falling” and “affordable” are two different words. A rate that slips a few hundredths of a point is not a bargain when it sits about a full point above last year. Even a bigger dip barely moves the needle, as a $400,000 loan saving just $25 shows.
Falling rates haven’t brought entry-level buyers back
Buyers aren’t exactly stampeding. According to Real Estate News, mortgage applications fell 1.2% for the week ending Oct. 30. Compared with the same week a year earlier, purchase applications were down 19% and refinance applications were down 60%.
So the small drop in rates isn’t enough to change behavior. People who can afford to wait are waiting, and the people who can’t are looking for help.
Family money fills the gap for first-time homebuyers
That help often comes from relatives. Fortune’s report centers on first-time buyers leaning on family for the down payment. Other surveys put the share of buyers getting family help at roughly 30% to 35%.
The newest National Association of Realtors data points the same way. Bloomberg reports that a record 10% of first-time buyers paid all cash in the year through June. Of those cash deals, 28% were backed by inheritance. In other words, family wealth is not just helping with down payments. It is paying for entire homes.
The first rung on the housing ladder is increasingly reserved for people whose families can pay for it. If your own savings are the whole plan, a rate near 7% hits your monthly budget directly, with no family cushion underneath.
That squeeze is part of a bigger pattern, which we explored in why homeownership feels like a fantasy.
What happens next for first-home buyers
The Mortgage Bankers Association forecasts the 30-year rate will stay above 7% through 2027. That outlook keeps homeowners with cheap loans locked in place. As a result, inventory stays tight and prices stay stubborn for first-time homebuyers and everyone else.
Freddie Mac usually updates its weekly survey on Thursdays, so the next reading should land Nov. 12. Real Estate News says upcoming jobs data could slow the recent slide in rates.
For first-time buyers, the math is blunt. The dream hasn’t gotten cheaper, but the price of waiting keeps going up too.